Low-cost options to boost mineral exploration and development in Canada
Our front-page recommendations are limited in scope, scale and financial impact on the federal fiscal framework. However, they are meant to provide material and meaningful benefits to mineral explorers and developers in Canada, spur new discoveries and boost domestic sources of minerals needed for our future. We have echoed these recommendations in previous pre-budget consultations and strongly re-emphasize the importance of acting now to protect Canadian advantages and stay on a path to meet the strategic goals laid out by government.
Investor exodus threatens Canadian market leadership
Canada is a world leader in connecting mineral projects with investment capital and minerals to supply chains. Our high standing has been built through a unique financial ecosystem that has been refined for nearly a century, with the Prospectors and Developers Association of Canada (PDAC) serving as a central industry voice for the past 94 years. While exploration and mining companies represent the largest share of listings on Canadian exchanges, the sector’s long-term competitiveness remains inextricably linked to the strength of our broader marketplace relative to other jurisdictions.
There are clear signals that the health of our capital marketplace is severely at risk, given that sectors outside of exploration and mining (i.e. energy, finance, transportation, etc.) have faced a stark decline in equity investment over the last four years. Canadian exchanges in 2025 generated barely one-third of the investment dollars recorded a decade ago or during the global financial crisis, whereas equity issuances on the NASDAQ have been effectively flat over the same timeframe.
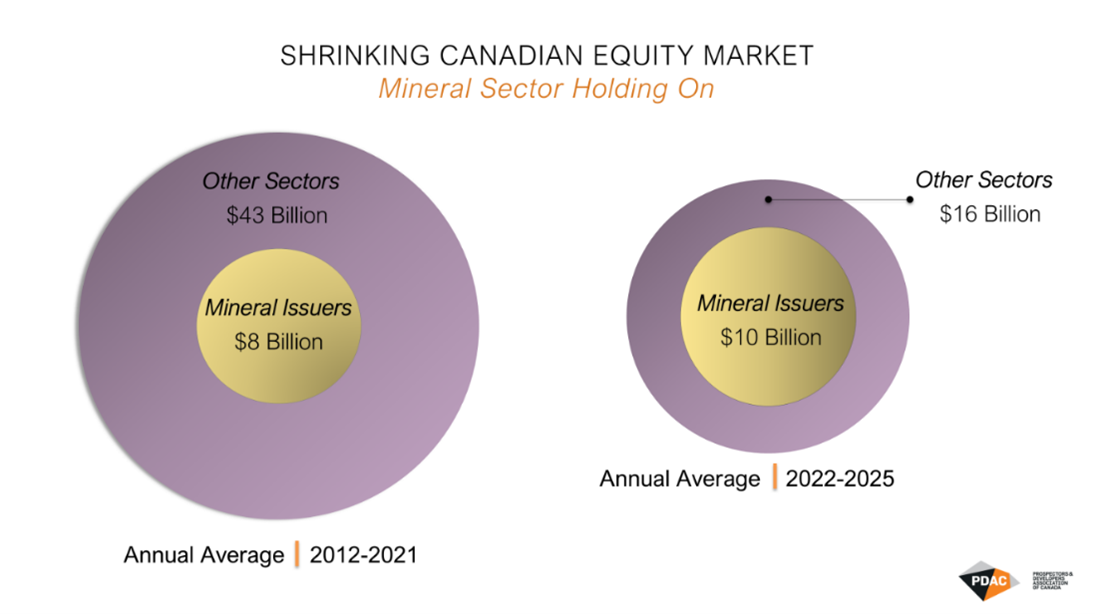
These warning signs tell us Canadian competitiveness is in jeopardy. Government must act with urgency to boost our investment attractiveness and protect our leadership in financing the global mineral industry. A sound first step is to maximize existing fiscal tools that offer negligible cost and immediate economic impact. For several decades, flow-through shares (FTS), the Mineral Exploration Tax Credit (METC) and, since 2022, the Critical Mineral Exploration Tax Credit (CMETC) have proven to fit this mould. Our analysis shows that FTS and mineral tax credits are low-cost, generate a positive long-term return on investment (ROI), and are essential in drawing investment to early-stage exploration.
Exploration incentives generate positive returns for Canadians
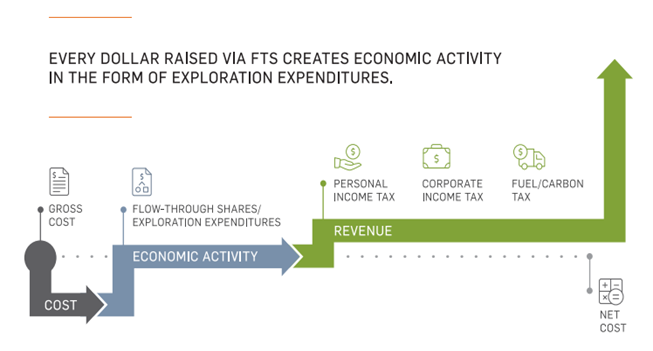
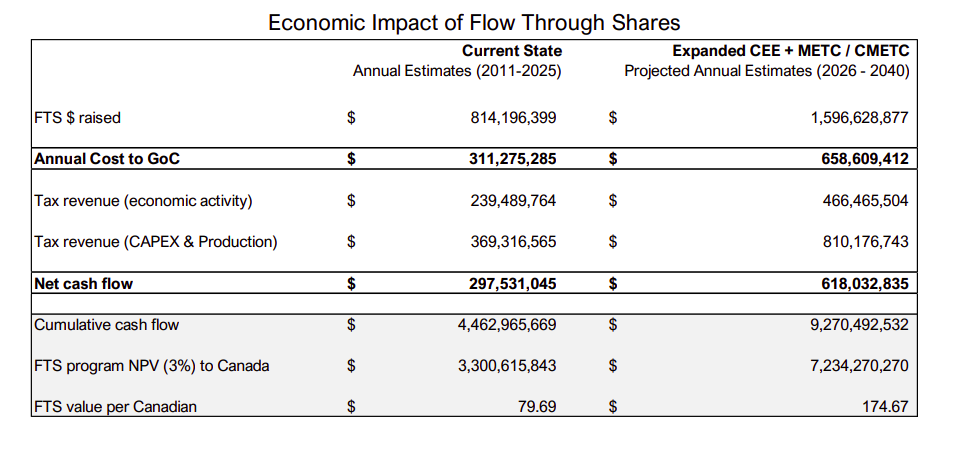
PDAC has developed a comprehensive financial analysis tool that investigates the effectiveness of the FTS regime in terms of its return on investment by the federal government deferring income tax revenue to spur exploration activity and new discoveries here at home.
As the following summary table shows, primary and secondary economic activity that we estimate is generated directly from FTS investment results in a net positive impact on federal coffers and the overall Canadian economy.
Expanding capital access and flexibility junior explorers
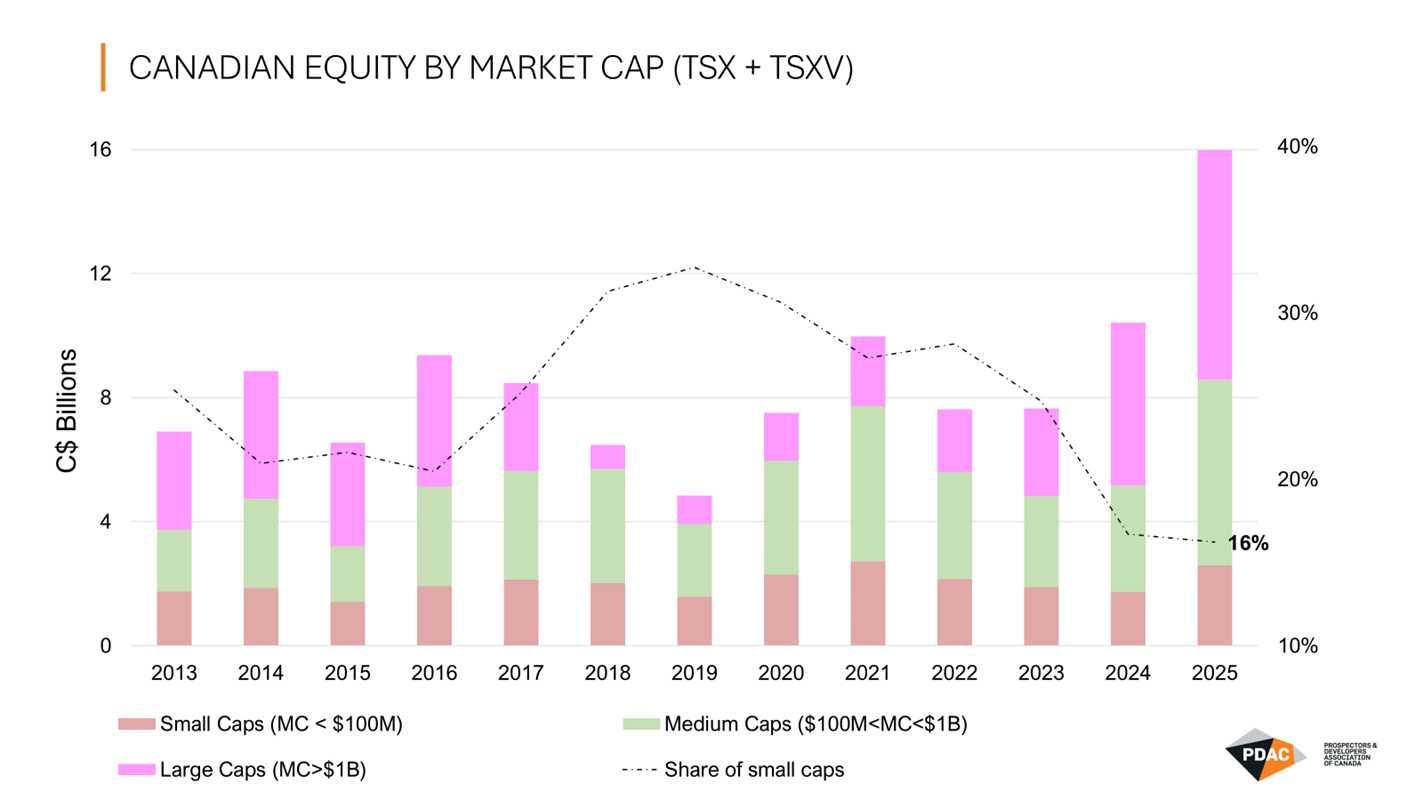
Roughly eight out of 10 companies in the mineral sector are small to medium-sized a with market capitalization below C$100 million, and this cohort is attracting a steadily shrinking share of investment. They captured only 16 per cent of the investment dollars raised in the market in 2025. The decline outlined below highlights the structural funding barriers faced by early-stage exploration companies is driving a decline in greenfield exploration activity.
Compounding the effects of a capital shortage for early-stage explorers, limitations on how companies can spend FTS funds create a chokepoint for mineral projects to reach the scoping and assessment phases necessary to determine the viability of developing a deposit. Ultimately, this gap in FTS expenditure eligibility has constrained the development of new mines in Canada.
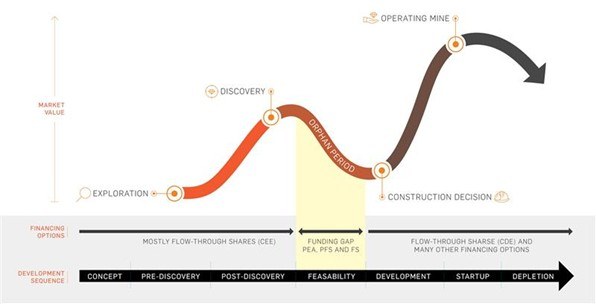
Historically, only one in 1000 advanced mineral projects becomes a new mine and S&P ranks Canada third last globally, estimating that it takes nearly 30 years on average for companies to work through regulatory and permitting processes from first discovery to building a mine.
With such long odds and timelines, attracting risk capital is extremely difficult and remains a perennial challenge for junior explorers. To counter part of this high risk, Canada’s unique FTS regime has generated more than two-thirds of domestic exploration activity over the last decade. Compounding the difficulty, the high-risk nature of exploration makes attracting hard dollars (i.e. non-FTS funds) to complete technical assessments and study work even more challenging.
To generate more Canadian mineral discoveries and move more projects towards economic feasibility, we recommend expanding CEE eligibility so companies can more efficiently direct FTS funds towards technical scoping and assessment work.
Securing long-term competitive advantages to drive discoveries
A decline in Canadian production in several primary commodities like copper and nickel is a striking reminder that the rate of mineral discovery and development is not keeping pace.
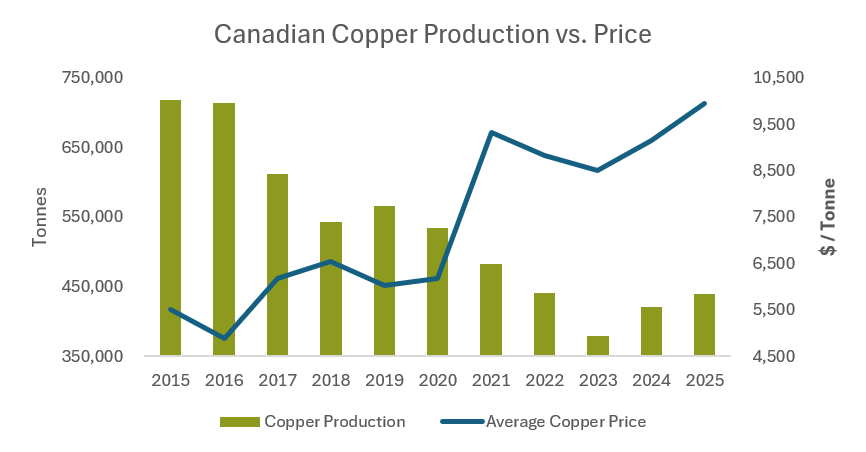
Increasing copper production, or the production of any other mineral, requires companies to discover resources and convert them into economically recoverable reserves through scoping and assessment work. While estimated resources for many minerals has climbed over the past decade, mineable reserves in Canada for many minerals, like copper below, have declined.
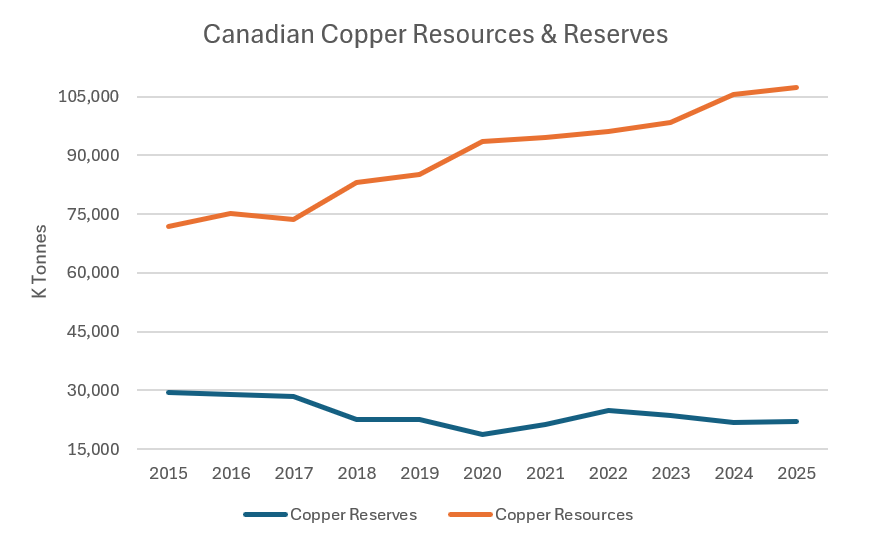
The widening gap between estimated resources and mineable reserves in Canada means the rate of discovery is not keeping up with depletion from mining and a key contributing factor is the tax treatment of exploration expenditures. Activities that define mineral resources are generally eligible for CEE, while the advanced technical and economic studies required to convert resources into reserves are typically ineligible for both CEE and CDE. This creates a financial barrier for work needed to advance discoveries toward production and reinforces a need to expand CEE eligibility. Failing to close this gap will lead to more discoveries languishing at initial exploration stages and keep viable Canadian mineral deposits from reaching future supply chains.
FTS accounted for roughly 5 per cent of all Canadian equity investment in 2025, reinforcing the importance of this mechanism in our marketplace and the tangible capital injection on the ground that it generates within 18 months, with a significant amount going towards remote and northern communities.
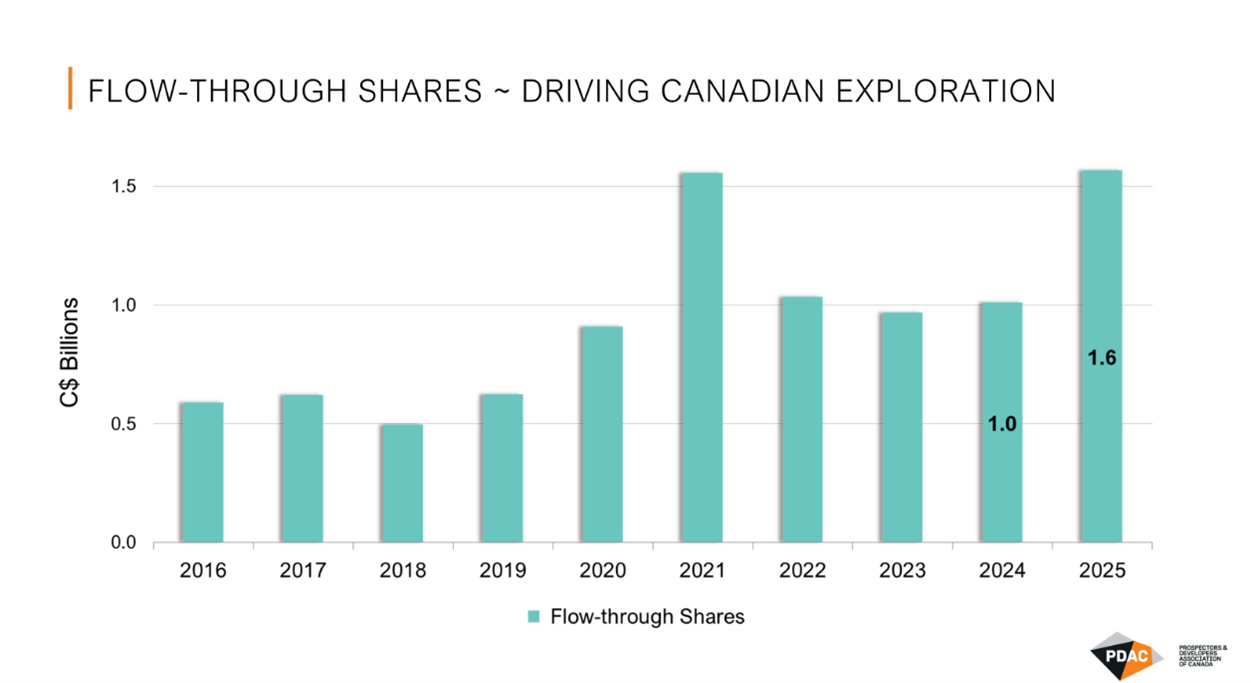
Without question, a primary driver behind the surge in flow-through investment in 2025 is an almost unrivalled upswing in commodity prices, which is not likely sustainable over the long term.

To protect against market fluctuations and ensure Canada can meet strategic commitments, a fiscal framework that supports new discoveries being made here at home over the long term is needed. Should commodities weaken, the METC and CMETC are the type of essential incentives that protect the mineral industry from such a downturn and maintain momentum for early-stage Canadian exploration projects.
Despite a two-year METC extension announced in March 2025, its renewal process through Bill C-15 took over a year, generating significant investor uncertainty over this time. Similarly, the CMETC is set to terminate in spring 2027, which means expiry could precede any renewal of this incentive. These disconnects underscore the need for a longer-term solution.
We recommend making the METC and CMETC permanent or at least renewing both credits for a minimum of 10 years with an option to renew at the midway point.
These credits are the primary funding source of early-stage exploration, which often occurs in areas with limited infrastructure. This grassroots activity in Canada declined materially from approximately 55 per cent of domestic exploration spending in 2001 to below 25 per cent in 2025.
Strong metal prices, renewal of the METC and launch of the CMETC in 2022 combined to drive a slight rebound in Canadian grassroots activity from 2021 to 2024, in contrast to the global trend. However, the overall trend is still down significantly and is leading towards a precipitous decline in Canada’s mineral production capacity.

Boosting public geoscience to drive investment, discovery and informed land-use
We must be cognizant that Canadian mine development is falling short of our future needs. As NRCan’s graphic below shows, only a handful of new critical mineral mines have opened in the last two decades.
New Critical Mineral Mines Built in Canada
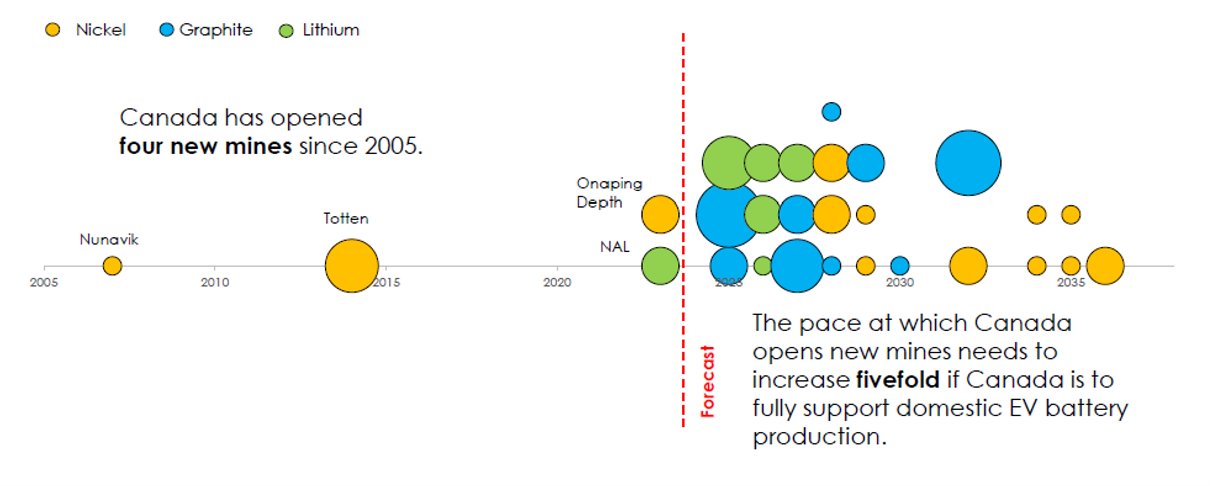
High-quality datasets and tools that come from public geoscience programs can be a catalyst for investment, reduce risk, improve capital efficiency, and accelerate the pace of discovery.
Public geoscience programs have proven merits time and again with research showing that every $1 in spending under the Targeted Geoscience Initiative (TGI) and Geo-mapping for Energy and Minerals (GEMS) program generated more than seven times the investment in economic benefit to Canada (Ernst & Young, 2019). Although public geoscience has played a key role in identifying and evaluating exploration opportunities in Canada, there remains significant opportunity to increase mineral exploration activity through the development of new geoscience data and research. Furthermore, we have seen the combined funding from federal and provincial governments for geoscience decline by more than 14% over the last decade and during a period where Canadian mineral exploration must increasingly target deposits at greater depths and remoteness.
The GEM - Geo North program is a prime example of public geoscience that can meaningfully inform exploration activities in northern regions where geological understanding is limited by sparse and uneven geological understanding. In all regions of Canada, work towards adding, modernizing, and infilling framework datasets as well as research of our mineral systems can upgrade existing mineral prospects and identify new ones to secure Canada’s future resource pipeline.
Looking outward, Canada is falling short of peers in funding new geoscience research, data distribution and leveraging academic partnerships. For comparison, Canada spends less than $20 million on public geoscience annually while Australia recently committed over A$566 million over 10 years to “fully map” minerals and resources; a roughly 5x-times differential on a per capita basis, relative to Canada’s geoscience efforts.
Public geoscience datasets and research provide the foundation for robust mineral potential assessments that should be central to evidence-based land management decisions. To ensure these assessments remain representative, they must be informed by modern, comprehensive, and high-quality geoscience data that is produced by public geoscience programs. As Canada advances its 30 by 30 conservation initiative, it is critical to integrate mineral potential assessments into land-use decision making that will ensure conservation objectives are balanced with the availability of lands needed to support future mineral development.
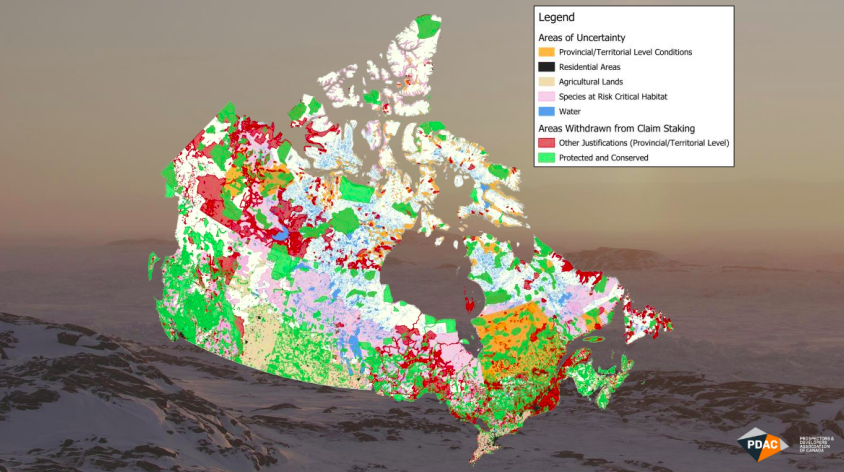
As PDAC’s land availability mapping highlights, accessing prospective land in Canada is becoming increasingly complex, and exploration is largely constrained to brownfield regions where previous mine development has occurred.
PDAC Mineral Exploration / Land Availability Mapping
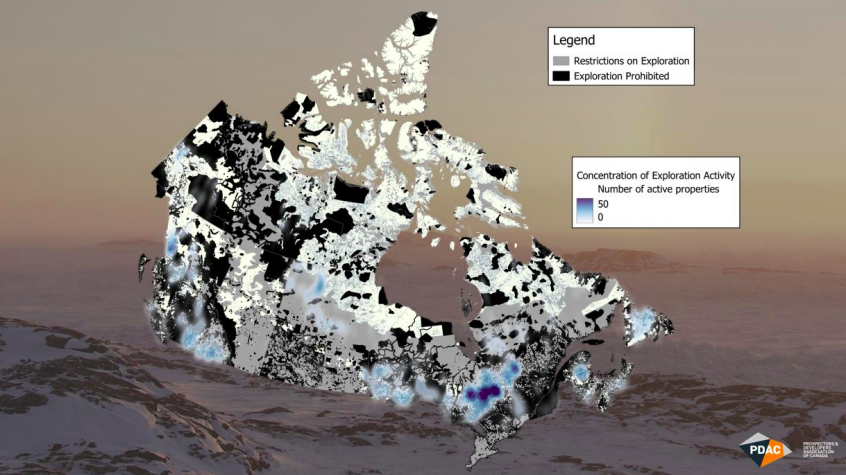
To attract investment, accelerate discoveries, reduce development timelines for new mines and ensure Canada’s efforts to protect and conserve lands and oceans consider what lies below the surface, we recommend increasing funding to the GSC for geoscience programming to a minimum of $30 million per year. The roughly $10 million per year increase would allow for the extension of the GEMS program beyond 2027 and correct TGI funding levels to account for two decades of inflation since the program launched, as calculated using the Bank of Canada’s formula. A portion of new funding should also be used to integrate outputs from GEMS, TGI and drill core scanning to: (1) develop comprehensive mineral potential models; (2) expand general accessibility of public geoscience data; and (3) facilitate evidence-based land conservation and protection decisions.
Closing an unintentional gap in the Income Tax Act
The definition of a “mineral resource” in section 248(1) of the Income Tax Act creates a gap in federal policy whereby some minerals on Canada’s critical list may not qualify as CEE unless the deposit is certified by the minister of natural resources. As a result, FTS / CMETC funds cannot go towards exploration for these minerals without written approval by the minister of natural resources. This definition shortfall adds uncertainty, time and costs for junior explorers. We recommend amending the definition of a mineral resource in the Act to cover all species on Canada’s critical mineral list, as was done in Budget 2023 for lithium brines.
Additional considerations to supercharge mineral exploration and development sector:
Additional recommendations to supercharge mineral exploration and development sector:
| Recommendation | Rationale |
| Allow unrestricted eligibility for a portion of FTS funds i.e. to cover general & administrative (G&A) costs. | FTS funds cannot currently be used for G&A. Companies may have sufficient funding for exploration activities but lack “hard dollars” that can prevent projects from advancing. Allowing some FTS proceeds to cover G&A would give more flexibility and help move stalled exploration projects forward. |
| Allow activities in paragraph (g) of CDE to be eligible under CEE (i.e. reinstate paragraph (f) in CEE to cover all activities to bring a mine into production). | There has been a drastic change in the strategic importance of minerals in Canada since FTS expense treatment changes occurred in 2013. Beyond our primary recommendation to expand CEE eligibility, restoring pre-2013 CEE treatment for pre-production mine-development expenses would provide further incentive to invest in and advance viable projects toward commercial production. |
| Adjust FTS capital gains treatment to be based on purchase price with limits, or for investors below the top income tax bracket, or for firsttime FTS purchasers. | According to CRA, approximately 13,000 high-income Canadians account for ~90% of FTS investment. FTS have unavoidable “phantom capital gains” given a nil cost-base treatment, which creates a disincentive for most Canadian retail investors. Amending the capital gains treatment would broaden the investor base for junior and early-stage exploration and make the FTS regime attractive to investors other than for tax planning purposes. |